


 Switch to seedless. Get 30% off with SWITCH30 till Nov 02


Tangem Pay for Travelers: Earn Cashback Abroad
You're abroad, your hotel is priced in a currency you don't hold, and your bank just charged you a foreign-transaction fee on top of a mid-market exchange rate it quietly marked up. A crypto travel card promises a way to spend directly from your crypto balance.
It can also remove the currency-loading step and offer cashback. Here's what Tangem Pay actually delivers on that promise, and where the caveats are worth reading before you board.
What Tangem Pay Is and How It Works
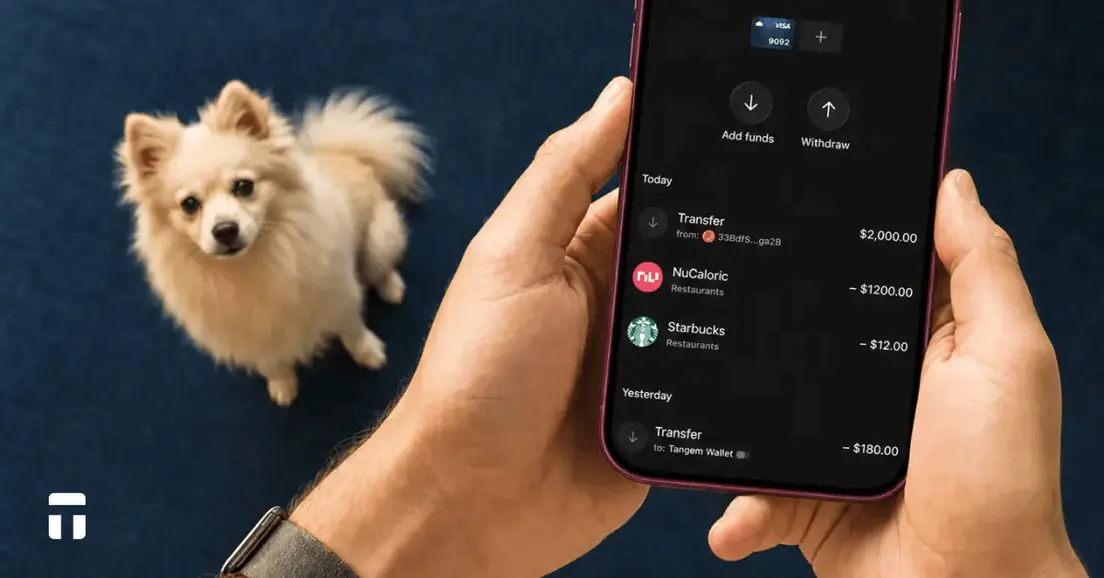
Tangem Pay is a non-custodial payment account built into the Tangem Wallet app. It gives you a Visa card funded with crypto or a U.S. bank account via ACH/FedWire.
Your funds sit in a smart contract, not on a custodial server. If the card is ever frozen or disconnected from the Visa network, your onchain USDC balance is unaffected.
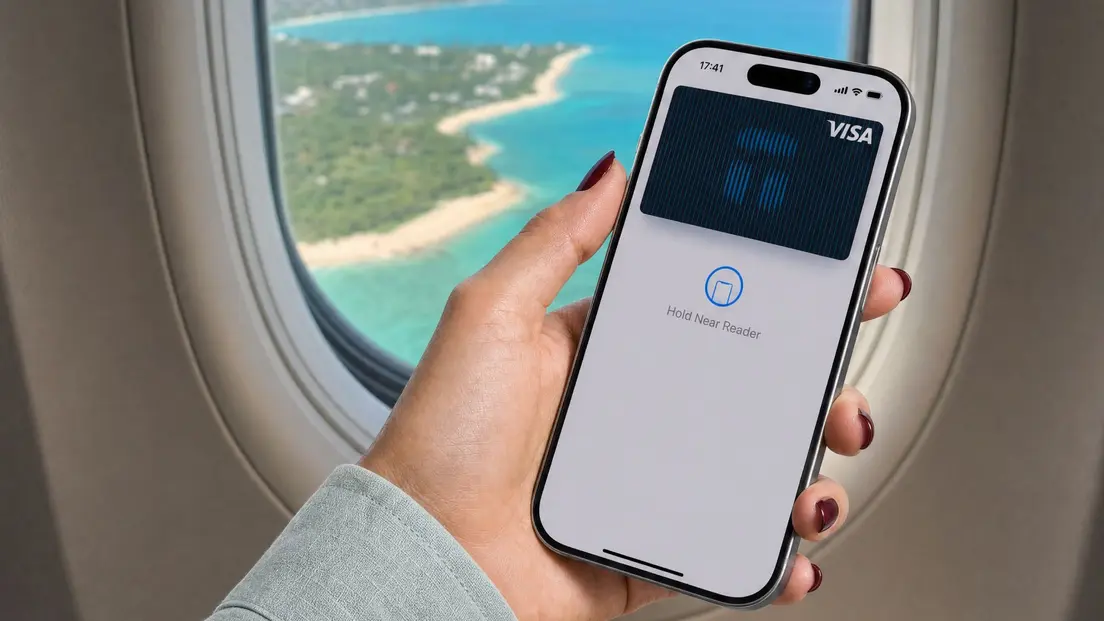
The Visa card can be added to Apple Pay or Google Pay for contactless in-store use, or you can enter the card details manually for online purchases. The Tangem Pay physical card (exclusive early bird edition) is now available.
Currency Conversion and Fees Abroad
USDC converts to USD at a 1:1 rate within the Tangem Pay system. For transactions in non-USD currencies, Visa foreign-exchange rates apply at the point of conversion. Those are the same rates Visa applies across its network globally.
Cashback on travel spending
Tangem Pay currently has two tiers: Basic and Plus. Basic members earn 1% cashback, capped at $100 per month. Plus members earn 2% on up to $300 per month. Cashback is paid in USDC, and purchases must be at least $30 to qualify.
For travelers, that rate compounds nicely on flights, hotels, and dining. A Plus member spending $5,000 on a two-week trip earns $100 in USDC back, assuming all purchases qualify.
If you're based in the EU or UK, cashback does not apply to in-store purchases at EU and UK merchants. That includes Apple Pay, Google Pay, and any physical-card tap transactions at those merchants. The reason is interchange-fee regulation, not a product limitation that Tangem can easily work around.
What works best for EU/UK cardholders?
Online purchases at EU merchants remain eligible, and purchases made outside the EU (for instance, spending in Southeast Asia, the US, or Latin America while traveling) are included. So if you're a UK resident flying to Bangkok for two weeks, your in-destination spending qualifies. Your pre-trip Amazon order qualifies. Your contactless coffee in London does not.
Topping Up While You're on the Road
You fund Tangem Pay with native USDC on Polygon, either from your Tangem Wallet or from another wallet that holds USDC on Polygon. That is one asset on one network, so check the chain before you send.
If you need to acquire USDC before or during a trip, the Tangem app includes four on-ramp providers: Mercuryo, MoonPay, Simplex, and Unlimit, all of which support purchases via Visa or Mastercard credit/debit cards, bank transfers, Apple Pay, or Google Pay. Crypto is delivered directly to your Tangem Wallet.
One practical note: top-up confirmation timing on-chain depends on Polygon network conditions. Before a trip, topping up a day in advance is sensible. Relying on an on-chain top-up at an airport gate is a plan, but it's not a guarantee.
Getting Set Up Before You Leave
Tangem Pay requires four things: a Tangem Mobile Wallet, the Tangem app, a supported region, and a one-time KYC verification. KYC is handled through Sumsub and requires two checks: a government-issued ID and face verification. Tangem does not see or store your identity data.
That KYC requirement is intentional. The Visa network mandates it for regulated payment products. The key distinction is between two accounts: KYC applies only to the Tangem Pay spending account, not to your main Tangem Wallet. Your main wallet's transaction history and holdings stay private. Only Tangem Pay activity is visible to compliance partners.
The Tangem Wallet and Tangem Pay are two separate accounts in the same app. The wallet is your self-custody holdings. Tangem Pay is the regulated spending layer on top.
For the hardware wallet itself, the Tangem card is credit card-sized and X-ray-safe, which matters for air travel. It has IP69K dust and water protection, operates between -25°C and +50°C, and connects via NFC with no battery or USB. The app requires iOS 16.0 or later (iPhone 8 and newer) or Android 6.0 and later with full NFC support. There's no desktop or web interface.
A pre-trip checklist worth running through:
- Confirm Tangem Pay is available in your home country during in-app onboarding
- Complete KYC before you leave (verification can take time)
- Top up your USDC balance on Polygon in advance
- Add the card to Apple Pay or Google Pay for contactless use
- Save your card details for online bookings
FAQ
-
Tangem Pay is accepted at Visa merchants in over 150 countries, but the card is currently available only to residents of the USA, Latin America, Asia-Pacific, and parts of the Middle East and Africa. EU and UK availability was planned for 2026. Merchant acceptance also depends on local laws, issuer controls, and category restrictions, so a Visa logo doesn't guarantee every transaction will go through.
-
Yes. If you are using the virtual Tangem Pay card (via Apple Pay or Google Pay on your phone), you can withdraw cash only at NFC-enabled contactless ATMs that support mobile wallets. Tangem Pay physical Visa cards that can be inserted into standard ATMs worldwide where Visa is accepted
-
Eligible purchases of at least $30 earn cashback at 1% (Basic) or 2% (Plus), paid in USDC. The terms list excluded merchant category codes, so specific booking platforms or travel categories may not qualify. Check the current cashback terms at tangem.com/docs/en/tangem-pay-cashback-terms.pdf before assuming a booking qualifies.
-
Yes, with a specific framing. In-store purchases at EU and UK merchants are excluded from cashback because of interchange-fee regulation. But purchases made outside the EU, including all your in-destination spending on a trip to Asia or the Americas, are eligible. Online purchases at EU merchants also qualify. The card works best as a travel card for EU/UK users rather than an everyday domestic cashback card.
-
Freezing the card disconnects it from the Visa network. Your on-chain USDC balance in the smart contract is unaffected. You can unfreeze the card in the app or transfer your USDC back to your main Tangem Wallet at any time.
-
KYC is required to use Tangem Pay because the Visa network mandates identity verification for regulated payment products. The process is handled by Sumsub and requires a government-issued ID and face verification. Tangem does not see or store your identity data. Your main Tangem Wallet requires no KYC.
-
Yes. You can send native USDC on Polygon from any compatible wallet to your Tangem Pay account. The Tangem app also includes on-ramp providers (Mercuryo, MoonPay, Simplex, and Unlimit) if you need to buy USDC directly with a bank card or Apple Pay.

Don't miss these 
Other articles

